
Last Updated: November 19, 2026
Quick Summary
To get a certificate of liability insurance, request it from your insurer or insurance agent, since only a provider, agent, or broker can issue a COI. Gather your policy number, policy dates, and the certificate holder’s exact legal name and address, then submit the request through your insurer’s online portal or by calling your agent.
- The American standard form most insurers use for a COI is the ACORD 25.
- A certificate holder can see your limits but has no rights under your policy, unlike an additional insured.
- A missing suite number or misspelled entity name is the most common reason a certificate gets rejected.
- Naming a venue or general contractor as certificate holder does not make them an additional insured.
- If the contract requires coverage you lack, buy the endorsement or ask the other party to revise the requirement.
Table of Contents
- What a Certificate of Liability Insurance Proves and Who Issues It
- What Information You Need Before You Request a COI
- How to Get a Certificate of Insurance Online
- A Certificate of Liability Insurance Example: Reading Your ACORD Form
- How Long Does It Take to Get a Certificate of Insurance?
- Getting a Certificate of Insurance for an Event or Construction Contract
- What to Do When a Certificate of Insurance Is Rejected
- Have Your Agent Request Your Certificate Today
- Frequently Asked Questions
What a Certificate of Liability Insurance Proves and Who Issues It
A certificate of liability insurance is a one-page document that proves your business holds active coverage. It shows a client or venue your policy limits, your insurer, and your policy dates. It does not change your policy. It only reports what you already carry.
This guide from United Family Insurance covers how to get a certificate of liability insurance in Las Vegas, Nevada, step by step. Below, we show you exactly who to ask, what to send them, and how to fix a rejected certificate.
One point most guides get wrong: the certificate must come from your insurer or agent. You cannot create one yourself, and a copy of your declarations page is not a substitute. As Illumend’s guide to certificates of insurance explains, only an insurance provider, agent, or broker can issue a COI.
Certificate of insurance (COI) is the short name for this document. The American standard form most insurers use is the ACORD 25.
Certificate Holder vs. Additional Insured
These two terms get mixed up constantly. They are not the same.
- Certificate holder: the person or company named on the COI who receives proof of your coverage. They can see your limits, but they have no rights under your policy.
- Additional insured: a party added to your policy by endorsement. They get actual protection under your coverage, usually for claims tied to your work.
A client asking to be a certificate holder wants proof. A client asking to be an additional insured wants coverage. The second request needs a policy change, and that can take longer. For a deeper explanation, see what a certificate of insurance for contractors covers.
What Information You Need Before You Request a COI
Gather the details first. Missing information is the main reason certificate requests bounce back and forth.
Have these ready:
- Your legal business name exactly as it appears on your policy
- Your policy number and the effective and expiration dates
- The certificate holder’s full legal name
- The certificate holder’s complete address
- A description of the work or event, if the contract asks for one
- Any additional insured or waiver requirements in the contract
- The deadline the client or venue gave you
Check the contract language closely. Some agreements ask for specific coverage limits or endorsements. If your policy does not match, tell your agent before the request goes out.
How to Get a Certificate of Insurance Online
Getting a COI online is usually the fastest route. Many insurers let policyholders log into their account and download a certificate online.
Here is the step-by-step process:
- Log in to your insurer’s online account. Use the policyholder portal, not a general quote page. If you have multiple policies with the same carrier, select the policy that matches the work or event.
- Find the certificates section. It is often labeled “Certificates of Insurance” or “Proof of Insurance.” Some carriers bury it under “Policy Documents.”
- Enter the certificate holder’s name and address. Copy them from the contract, not from memory. A missing suite number or a misspelled entity name is the most common reason a certificate gets rejected.
- Add any required endorsements. Mark additional insured or waiver of subrogation if the contract demands it. If the portal does not offer those options, the request must go to your agent.
- Submit the request. Some insurers issue certificates directly. Others route requests to an agent for review, especially when endorsements are involved.
- Download or email the PDF. Send it to the client or venue and save a copy for your records. Keep the confirmation email in case the recipient says it never arrived.
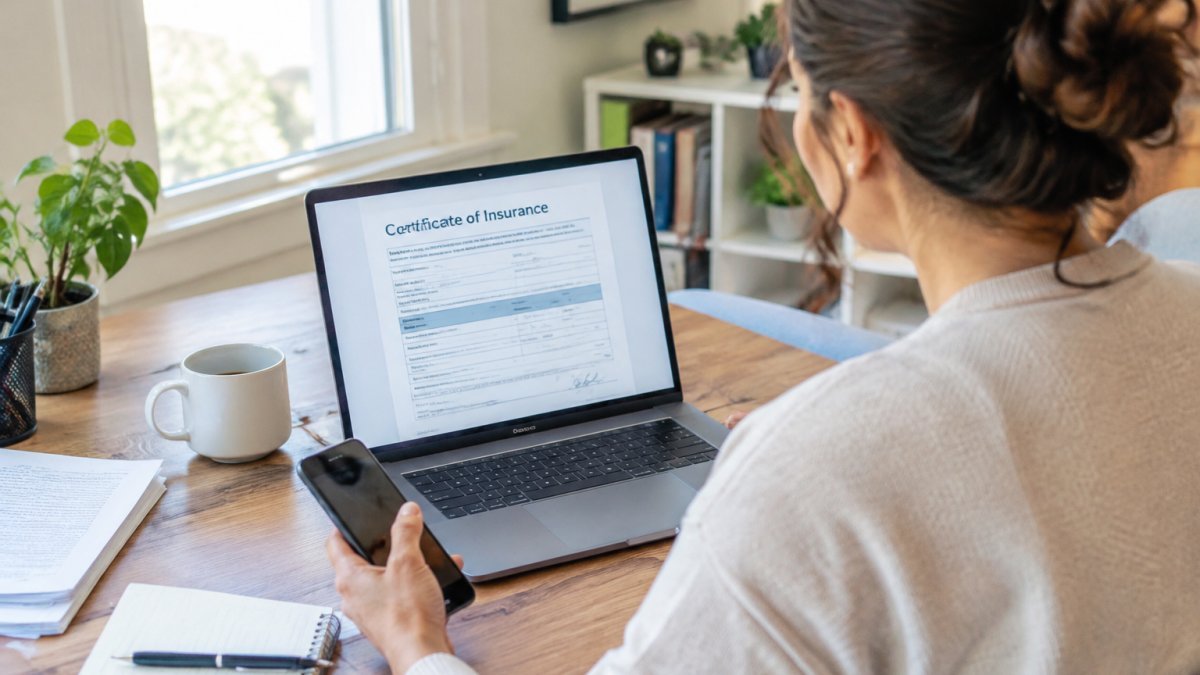
If your insurer has no online portal, call your agent. A common mistake is requesting a certificate from the wrong carrier, so confirm which policy the client needs to see. Contractors can review Nevada general liability requirements and COI steps before submitting.
When the portal will not cooperate. If the certificate does not generate, avoid repeatedly resubmitting the same request. Call your agent with the policy number and the certificate holder’s exact legal name.
Urgent requests. If a venue or general contractor needs the certificate before a deadline, tell your agent the deadline up front and send the contract page that lists the insurance requirements.
Watch out: downloading a certificate from the portal does not change your policy. If the contract requires additional insured status and the portal only lets you name a certificate holder, the document will be rejected. Ask your agent about the endorsement before you send anything.
A Certificate of Liability Insurance Example: Reading Your ACORD Form
Reading a certificate of liability insurance example takes about two minutes once you know the layout. The ACORD 25 form follows a fixed structure, so the same fields appear every time.
| Section | What It Shows | Why It Matters |
|---|---|---|
| Producer | Your agent or broker and their contact details | Tells the client who issued the form |
| Insured | Your business name and address | Confirms the policyholder matches the contract |
| Insurers | The carrier names and NAIC numbers | Lets the client verify the source |
| Coverage lines | General liability, auto, umbrella, workers’ comp | Shows which policies back the work |
| Limits | Per-occurrence and aggregate amounts | Must meet the contract’s minimums |
| Dates | Effective and expiration dates | Proves coverage is active now |
| Certificate holder | The client or venue name and address | Must match exactly |
| Description of operations | Notes on the project or additional insured status | Explains any special terms |
The bottom right box is where additional insured wording appears. If it is blank, the holder is not an additional insured, no matter what the contract asks for.
How Long Does It Take to Get a Certificate of Insurance?
Timing depends on the request. Certificates can be available quickly through an online portal, while agent-issued certificates and requests involving endorsements can take longer. Plan ahead for deadlines, and contact your agent or carrier for current timing on your policy.
Getting a Certificate of Insurance for an Event or Construction Contract
Event venues and construction contracts often have detailed certificate requirements. Review the contract carefully before the job or event begins.
For an event, venues commonly ask for:
- General liability with limits set in the venue agreement. Limits vary by venue and event type, so read the contract rather than assuming a standard amount.
- The venue named as certificate holder or additional insured. Many venues ask for both, and some ask for the venue’s parent entity or management company by its exact legal name.
- A specific date range covering setup, the event, and teardown. A certificate that expires on the event date can fail if load-out runs past midnight.
- Workers’ compensation proof if you bring staff, including contractors and temporary event staff.
- A waiver of subrogation in some venue agreements, which requires a policy endorsement rather than a certificate change.
Construction contracts add more. General contractors often require additional insured status, waiver of subrogation, and completed operations coverage. They may also specify primary and non-contributory wording, a project-specific aggregate limit, or a minimum number of days’ notice before cancellation. Review workers’ compensation requirements for contractors before you sign, since many construction agreements require proof of workers’ comp alongside general liability.
The practical step is to send your agent the insurance requirements section of the contract, not just the certificate holder’s name. The agent can compare each requirement, limits, additional insured status, waiver of subrogation, primary and non-contributory wording, against what your policy actually provides.
Watch out: naming a venue or general contractor as certificate holder does not make them an additional insured. If the contract requires additional insured status, the certificate must show the endorsement, and that requires a policy change through your carrier.
Confirm the requirement with the requesting party in writing. A certificate of liability insurance is issued by your insurer or agent.
What to Do When a Certificate of Insurance Is Rejected
A rejected certificate is usually a formatting or wording problem, not a coverage problem. Fix it by finding out exactly what the client flagged.
Common rejection reasons:
- The certificate holder’s name or address does not match the contract
- Required limits are lower than the contract minimums
- Additional insured status is missing
- The expiration date falls before the project ends
- The description of operations is blank when the contract requires one
Ask the client for the specific objection in writing. Then send that note to your agent with the corrected details. If the contract asks for coverage you do not have, you have two choices: buy the endorsement or renegotiate the requirement.
Rejections are common with large venues and general contractors. Do not resend the same document and hope it passes.
Have Your Agent Request Your Certificate Today
The fastest path to a clean certificate is a single call to your agent. They know your policy, your limits, and what each carrier needs to issue the form correctly.
At United Family Insurance, we handle certificate requests for Las Vegas business owners every week. Our agents compare the market for you, explain your coverage in plain terms, and coordinate with carriers so your certificate reaches the client on time. If you are still deciding how to buy coverage, our guide to business liability insurance in Nevada walks through the requirements and steps. You can also read our comparison of local versus online insurance options to see how agent support differs from a self-service portal.
Get started with United Family Insurance and put your certificate request in expert hands. Get Quote
Frequently Asked Questions
Where do I get my certificate of liability insurance?
Your certificate of liability insurance must come from the insurance provider, agent, or broker that issued your policy. You cannot create one yourself. Contact your insurer or agent, tell them who is requesting the certificate and why, and provide the certificate holder’s exact business name and address. Many carriers also let you download a certificate of insurance online through your policyholder account.
What information do I need to request a certificate of insurance?
You need the certificate holder’s full legal business name and address, the specific coverage limits and policy types they require, and any additional insured or waiver of subrogation endorsements written into the contract. Have your policy number and effective dates ready. For events, include the venue’s exact entity name and the event date. A certificate of liability insurance example from the requesting party’s contract helps you match their requirements precisely and avoid a rejected certificate.
Can I get a certificate of insurance online, and how long does it take?
Yes, many insurers let policyholders log into their online account and download a certificate of insurance instantly. If your carrier does not offer self-service, your agent or broker can issue one. Contact your agent directly about timing for urgent requests. The certificate reflects your active policy, so confirm coverage limits and additional insured requirements before submitting it to the certificate holder.
What is the difference between a certificate holder and an additional insured?
A certificate holder is the party named on the COI who receives proof of your coverage, such as a landlord or venue. Being named as a certificate holder does not give them any rights under your policy. An additional insured is formally added to your policy through an endorsement, giving them protection under your liability coverage if a claim arises. If a contract requires additional insured status, your agent must process an endorsement, which can take longer than issuing a standard certificate.
